Grow Your Brand Branding Guide 2026-05-10
Grow Your Brand Plain brand guides for clearer words, stronger proof, and cleaner decisions.

Historical brand decision

Klarna: Checkout BNPL trust

A payments brand moved credit into the retail checkout by making timing, approval, repayment, reminders, and merchant placement part of the shopping experience. Checkout finance needs more than conversion.

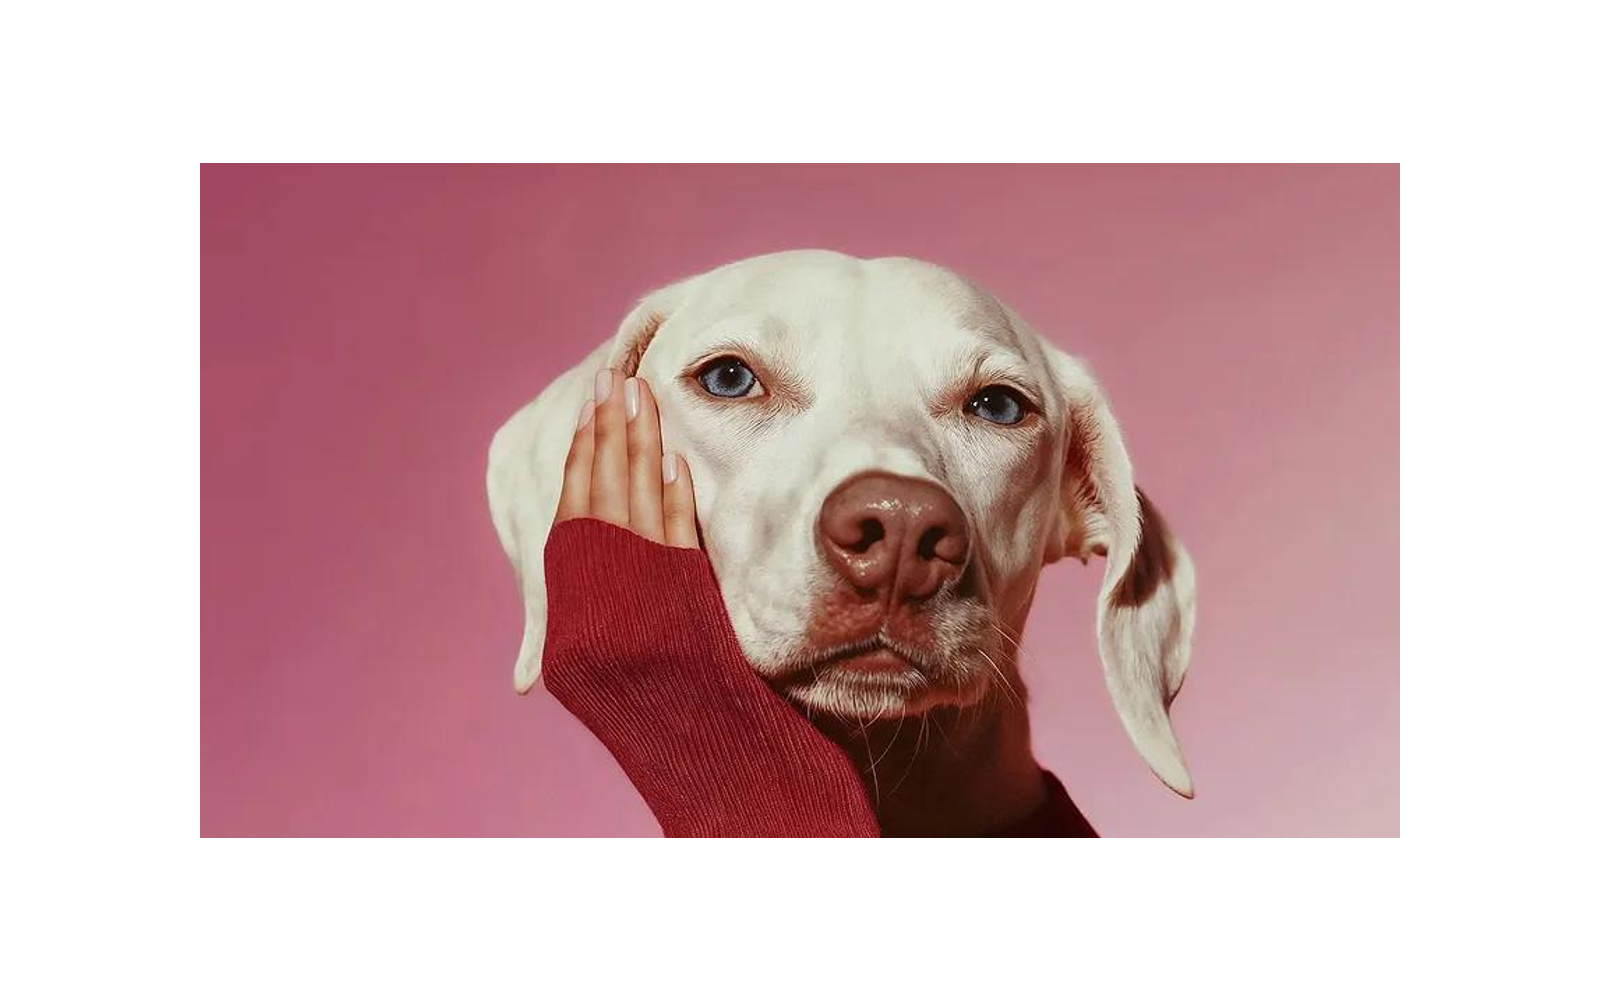
Klarna campaign showing a dog held by a person

Klarna: Checkout BNPL trust

Historical brand decision ยท 3 sources

Source image: Klarna, About us. Image source
In this guide 8 sections
01

Short Answer

Klarna: Checkout BNPL trust is a trust case about Klarna in 2005-present. A payments brand moved credit into the retail checkout by making timing, approval, repayment, reminders, and merchant placement part of the shopping experience. Checkout finance needs more than conversion. The brand has to make cost, timing, approval, repayment, reminders, late fees, and eligibility clear enough that trust survives after the purchase.

02

What Klarna teaches

  • Klarna was founded in Stockholm in 2005.
  • Klarna's public materials position the company around payment flexibility, shopping services, and merchant checkout.
  • The useful brand system is the payment moment: offer, approval, schedule, reminder, app record, and merchant trust.
  • Buy now, pay later creates brand risk when the repayment promise feels easier to enter than to understand.
  • The operator lesson is to design the post-purchase obligation as carefully as the checkout button.
03

What Changed

A payments brand moved credit into the retail checkout by making timing, approval, repayment, reminders, and merchant placement part of the shopping experience.

04

The Decision Context

Checkout is a fragile place to build a brand. The customer is deciding, the merchant wants conversion, and the payment provider is asking for trust in a few seconds. Klarna made that moment feel softer, more retail-friendly, and more visible than ordinary credit.

The pink cue, simple payment options, app layer, reminders, merchant placement, and repayment schedule all point to the same promise: buy now, pay later without making the payment step feel like a bank form.

05

The Button Changed The Credit Context

Klarna's brand sits close to the merchant, not far away in a separate finance office. That placement changes the meaning of credit. It feels like part of shopping behavior, which can help conversion and make the payment option easy to remember.

The risk follows the same path. If the checkout offer is easy but the repayment terms feel vague later, the brand gets the blame. Klarna's trust job is to make the schedule, reminders, fees, and eligibility as visible as the approval.

06

The App Became The Memory Layer

Klarna's app and shopping services matter because a payment decision does not end at checkout. The customer still needs to know what was bought, what is owed, when payment happens, and where the order sits.

That turns the brand into a post-purchase record. The strongest checkout brands do not disappear after approval. They help the customer understand the obligation they accepted.

07

Decision lesson

Klarna belongs in the guide because it shows how a financial product can be redesigned as a retail behavior. The soft visual system and checkout placement made payment flexibility feel normal.

For operators, the lesson is blunt: if you make buying easier, make remembering the cost easier too. Conversion without repayment clarity becomes a trust problem.

08

People Also Ask

What happened to Klarna?

Klarna: Checkout BNPL trust is a trust case about Klarna in 2005-present. A payments brand moved credit into the retail checkout by making timing, approval, repayment, reminders, and merchant placement part of the shopping experience. Checkout finance needs more than conversion. The brand has to make cost, timing, approval, repayment, reminders, late fees, and eligibility clear enough that trust survives after the purchase.

Why is Klarna a trust case?

Klarna is filed as a trust case because the visible consequence sits in that decision pattern. A payments brand moved credit into the retail checkout by making timing, approval, repayment, reminders, and merchant placement part of the shopping experience.

What can brands learn from Klarna?

Checkout finance needs more than conversion. The brand has to make cost, timing, approval, repayment, reminders, late fees, and eligibility clear enough that trust survives after the purchase.

09

Sources

Historical evidence recorded 2026-05-10. Dates and outcomes belong to the period described.